Clio and Xero for Law Firms: What Attorneys Should Know About Their Financial Workflow
October 13, 2026
Law firms often use more than one system to manage their financial information.
A practice management platform may contain client and matter information, time entries, invoices, payments, expenses, and trust activity. An accounting platform may contain the firm’s financial records, bank activity, expenses, liabilities, and financial reports.
When those systems are connected, it can reduce some duplicate data entry and make information easier to move between different parts of the firm’s workflow.
But an integration does not automatically mean the firm’s books are accurate.
For attorneys and law firm owners, one of the more important questions is not simply whether Clio and Xero can connect. It is whether the financial workflow between the systems is set up properly, consistently maintained, and reviewed when something does not match.
This distinction matters because financial information can move between systems without necessarily being complete, correctly categorized, properly reconciled, or ready to support financial decisions.
If your firm uses Clio Manage and Xero, understanding what happens between the two systems can help you ask better questions about your firm’s bookkeeping and financial processes.
1. Why Law Firms Use More Than One Financial System
A law firm’s financial information does not always begin in the accounting system.
For example, an attorney may record time against a matter in a practice management system. An invoice may then be created from that activity, a client may make a payment, and the resulting financial information may need to be reflected in the firm’s accounting records.
At the same time, the firm may have expenses, payroll, bank transactions, bills, and other accounting activity that originates outside the practice management system.
This means the firm may have several places where financial information is created, stored, or reviewed.
That is not necessarily a problem.
The problem arises when the firm does not have a clear understanding of which system is responsible for what information and how those records should relate to one another.
For a firm using Clio Manage and Xero, Clio may be used for practice and matter activity while Xero serves as the firm’s accounting system. The two systems can work together, but they do not necessarily need to contain identical information.
The goal is to create a workflow where information moves appropriately and the resulting accounting records can still be reviewed and reconciled.
2. Clio and Xero Serve Different Purposes
One of the easiest ways to become confused by an integrated financial system is to assume that every system should show the same information.That is not necessarily how a well-designed workflow works.
Clio Manage is designed around the law firm’s practice operations, including clients, matters, time, billing, payments, and related activity.
Xero is an accounting platform used to maintain the firm’s broader accounting records and financial information. Xero also provides accounting features such as bank reconciliation, expense tracking, invoicing, and financial reporting.
The systems therefore answer different questions.
Clio may help answer questions such as:
- What work was performed?
- Which client or matter does the activity relate to?
- What has been billed?
- What payments have been recorded?
- What matter-related financial activity has occurred?
Xero may help answer questions such as:
- What is the firm’s income?
- What expenses has the firm incurred?
- What is the firm’s cash position?
- What liabilities does the firm have?
- What do the firm’s financial statements show?
The objective is not necessarily to make both systems look identical.
The objective is to make sure the information that needs to connect between them is handled consistently.
3. What Happens When Clio and Xero Are Connected?
Clio currently offers an integration with Xero that can transfer supported information between the two systems. According to Clio’s current integration documentation, supported data can include contacts, time and expense activities, bills, credit notes, interest, and Clio Payment transactions. The exact information and workflow depend on how the integration is configured.
Supported information can flow between Clio and Xero, while other information has specific limitations. The direction of the data flow can also depend on the type of information and the integration settings. In addition, not every field or accounting detail is supported across both systems.
For example, Clio currently states that trust account transactions cannot sync from Clio to Xero due to limitations in Xero. Instead, Clio provides trust-related reports that can be compared with bank statements or information in Xero as part of the reconciliation process.
External source: Clio — Xero and Clio integration documentation
This is where law firm owners should understand an important distinction:
An integration moves supported information. It does not replace bookkeeping review.
When information moves from one system to another, the firm still needs to know:
- Where the original transaction was created
- Which system should be considered the primary record for that activity
- What information is being transferred
- How the transaction is categorized
- Whether the information reached the correct destination
- Whether anything requires manual review
- How the resulting accounting activity will be reconciled
This is especially important because different types of transactions can follow different workflows. The fact that two systems are connected does not mean every transaction follows the same path.
4. Your Bookkeeper Should Understand the Flow of Information
Law firm owners do not need to know every technical detail of an integration.
But you should be able to understand the basic financial workflow.
For example, if a bill is created in Clio and information is transferred to Xero, your bookkeeping process should account for what happens after that information arrives in the accounting system.
A bookkeeper may need to consider:
- Whether the transaction was transferred as expected
- Whether the correct account was used
- Whether the client or matter information is appropriate
- Whether the transaction duplicated an existing entry
- Whether the payment was recorded correctly
- Whether the related bank activity agrees with the accounting records
The same principle applies to supported information that originates or is updated in Xero and is expected to be reflected in Clio.
A good workflow begins with knowing where information originates and where it is supposed to go.
Without that understanding, troubleshooting can become a matter of comparing numbers after something has already gone wrong.
5. An Integration Does Not Mean Everything Is Automatic
Automation can reduce repetitive work, but it should not create the expectation that financial information never needs to be reviewed.
There are several reasons a transaction may still require attention.
For example:
- A transaction may not have synced as expected.
- A mapping may not be configured correctly.
- A transaction may have been entered manually in both systems.
- A payment may not correspond to the expected invoice.
- An expense may need to be reviewed before it is treated as a particular type of financial activity.
- A correction may require attention in one system without simply being copied into another.
The purpose of bookkeeping review is not to undo automation.
It is to make sure automation is producing the expected result.
This is an important distinction for law firm owners because the most efficient financial workflow is not necessarily the one with the fewest human touches.
Sometimes the right process is to automate repetitive activity and preserve human review where accounting judgment is needed.
6. Trust Accounting Requires Additional Attention
Trust accounting is one area where law firms cannot afford to assume that an integrated system has eliminated the need for review.
Client funds must be handled separately from the firm’s own operating funds, and law firms must follow the trust-accounting and recordkeeping requirements that apply in their jurisdiction.
Clio’s current Xero integration documentation states that trust account transactions cannot sync from Clio to Xero due to limitations in Xero. Instead, Clio provides trust-related reports that can be compared with bank statements or information in Xero as part of the reconciliation process.
This makes trust accounting an especially important example of why connecting two systems does not eliminate the need for review. Having trust-related information available in software does not by itself establish that the firm’s trust records are complete or properly reconciled.
Depending on the firm’s workflow and applicable requirements, trust-accounting review may involve comparing information such as:
- Trust account bank activity
- Client or matter trust balances
- Individual client ledgers
- Deposits
- Disbursements
- Transfers
- Accounting records
- Reconciliation results
The important question is not simply:
“Does the software show the right balance?”
It is:
“Can that balance be supported by the underlying records and reconciliations?”
If the numbers do not agree, the difference should be investigated.
That is where bookkeeping knowledge and trust-accounting procedures remain important, even when technology is doing part of the work.
7. What Should Happen When Clio and Xero Don't Match?
Differences between systems should not automatically be treated as software problems.
A discrepancy can have many possible causes.
For example, information may have:
- Been entered in one system but not the other
- Been entered twice
- Been categorized differently
- Failed to transfer as expected
- Been corrected in one system without the corresponding record being updated
- Been recorded at different points in the workflow
The first step is to understand the source of the difference.
A useful review may ask:
Where did the transaction originate?
Then:
What should have happened to it?
Then:
What actually happened?
Finally:
What needs to be corrected, and where?
This approach is more useful than simply changing numbers until the two systems appear to agree.
The goal is to identify the reason for the discrepancy and correct the underlying process when necessary.
8. Don't Create Duplicate Work Just Because You Have Multiple Systems
One of the reasons firms connect systems in the first place is to reduce unnecessary duplicate data entry.
Without a defined workflow, however, a firm can end up maintaining the same information in multiple places.
For example, someone might:
- Enter information into Clio.
- Manually enter the same information into Xero.
- Maintain a separate spreadsheet.
- Compare the records at month-end.
- Correct differences that could have been avoided earlier.
That process creates additional work and additional opportunities for errors.
A better workflow starts by determining which information should be entered once, which system should receive it, what information should transfer, and which items require review.
The goal is not to eliminate every manual task.
The goal is to eliminate unnecessary manual tasks while keeping the controls and review that the firm’s financial records require.
9. Month-End Bookkeeping Still Matters
A connected workflow can make month-end bookkeeping more organized, but it does not eliminate the month-end close.
The close is where the bookkeeper brings together the firm’s financial activity and reviews whether the records are complete, consistent, and ready for reporting.
Depending on the firm’s needs, this may include:
- Reconciling bank accounts
- Reconciling credit cards
- Reviewing income and expenses
- Investigating unusual transactions
- Reviewing outstanding items
- Reconciling trust accounts
- Reviewing accounts payable and receivable
- Recording necessary adjustments
- Reviewing financial statements
Information from Clio can be useful during this process because it provides context around billing, payments, matters, and other practice activity.
Xero can provide the accounting records and financial reporting needed to review the firm’s broader financial position.
External source: Xero bank reconciliation software
The bookkeeper’s role is to bring those pieces together appropriately.
That is different from simply checking whether two software screens show the same number.
10. What Attorneys Should Ask About Their Clio and Xero Workflow
Law firm owners do not need to become experts in integrations to have a better understanding of their financial systems.
A few practical questions can help.
Where does our financial information originate?
Do invoices begin in Clio? Do expenses begin somewhere else? Where are payments recorded?
Understanding the starting point helps clarify the rest of the workflow.
What information moves between systems?
Not every transaction necessarily follows the same process.
Your bookkeeper should be able to explain what is expected to transfer and what still requires manual review.
Which system should I rely on for each type of information?
The answer may differ depending on whether you are looking at matter activity, billing, payments, bank activity, expenses, or financial statements.
How are discrepancies identified?
If Clio and Xero don’t agree, there should be a process for finding out why.
Are trust records being reconciled appropriately?
Trust accounting should not be treated as simply another type of financial transaction.
Ask how trust activity is reviewed and reconciled against the appropriate records.
How does the workflow affect month-end?
Your technology should support the bookkeeping process rather than create another layer of work at the end of every month.
The Goal Is a Financial Workflow You Can Understand
Technology can make a law firm’s financial processes more organized, but the technology itself is not the financial process.
The process includes the people, procedures, accounting structure, reconciliations, reviews, and controls surrounding the software.
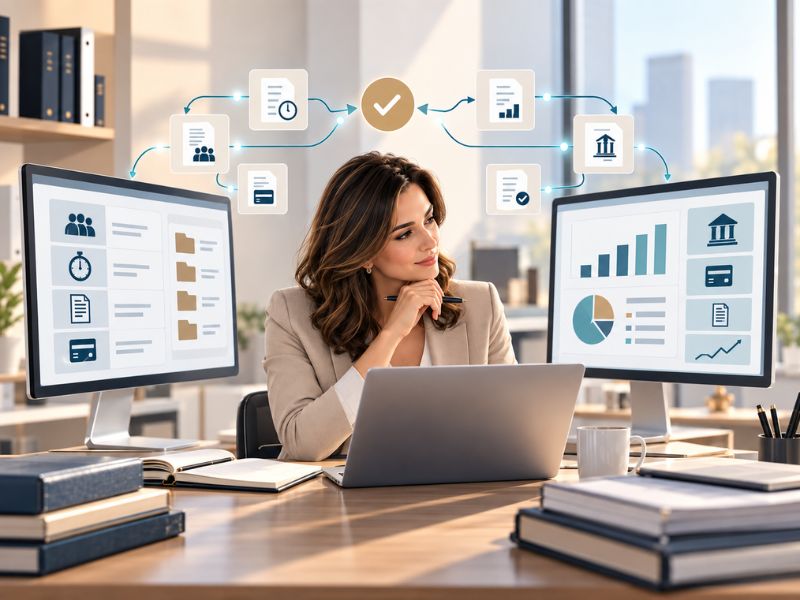
For a law firm using Clio and Xero, that means understanding how practice and matter activity connect with the firm’s accounting records, where information originates, what should transfer, and which areas still require human review.
It also means reconciling the firm’s financial records rather than assuming that connected systems automatically make those records accurate.
For attorneys and law firm owners, the important question isn’t simply whether Clio and Xero are connected. It’s whether the financial workflow around those systems is working as intended.
A well-organized workflow can reduce unnecessary data entry and make information easier to trace. But reliable bookkeeping still depends on consistent procedures, appropriate account structures, timely reconciliation, and knowledgeable review.
That is particularly important for law firms because financial information can involve client matters, trust funds, operating accounts, billing, payments, and legal-specific reporting responsibilities.
Clio and Xero can be part of that workflow, but the technology should support the firm’s bookkeeping process—not replace it.
If you’re unsure whether your current bookkeeping processes are keeping up with the way your firm operates, a conversation with a legal bookkeeping professional can help identify areas that may need attention.
The Legal Accountant helps boutique law firm owners align their books, trust accounts, financial processes, and business goals to support financial information that is organized, reliable, and useful.
Ready to discuss your firm’s bookkeeping and financial processes? Book a Free Fit Call with The Legal Accountant.
Related Insights
Recent Posts
- Clio and Xero for Law Firms: What Attorneys Should Know About Their Financial Workflow
- When Accurate Books Aren’t Enough: The Financial Framework Growing Law Firms Need
- 7 Signs Your Law Firm Has Outgrown Its Financial Processes
- Growing Law Firms Need More Than Revenue—They Need Strong Financial Systems
- Can You Really Take Time Off From Your Law Firm?
- Why Law Firm Financial Problems Usually Start in the Bookkeeping Process (Not the Reports)
- Are Your Financial Reports Misleading You? How Law Firms Can Tell If Their Numbers Are Reliable
- The Hidden Risks of DIY Bookkeeping in Law Firms
- Why Your Law Firm’s Financial Reports Don’t Match Reality (and What That Means for Your Decisions)
- Beyond the Balance Sheet: How Financial Wellness Fuels Personal Wellness for Lawyers
Let’s simplify your law firm’s finances—starting today.
Expert financial support for legal professionals.
Quick Links
Contact Info
- Moses Lake, WA. 98837
- 509.761.6852
- hello@thelegalaccountant.com
© 2025 The Legal Accountant. All Rights Reserved.
Let’s simplify your law firm’s finances—starting today.
Expert financial support for legal professionals.
Quick Links
Contact Info
- Moses Lake, WA. 98837
- 509.761.6852
- hello@thelegalaccountant.com
© 2025 The Legal Accountant. All Rights Reserved.
Let’s simplify your law firm’s finances—starting today.
Expert financial support for legal professionals.
Quick Links
Contact Info
- Moses Lake, WA. 98837
- 509.761.6852
- hello@thelegalaccountant.com
© 2025 The Legal Accountant. All Rights Reserved.